AI Financial Analysis: Explain Expenses with Your ERP
Why did an expense increase? Learn how to connect ERP figures, transactions, and supporting documents to explain variances against budget and prior periods, with finance team review.
AI financial analysis should answer something more useful than “expenses increased”: Which transactions explain the difference, which vendors and cost centers do they belong to, and what supporting documents back up the explanation? For finance leaders, a convincing answer requires reconciled figures and accessible evidence.
On November 4, 2026, IT Brief Canada reported the launch of AskDost. According to the vendor, its assistant can connect income statement line items to the invoice lines that explain them and prepare actions subject to human approval. This is a capability announced by the company, not an independent validation of results, as covered in the article about the AskDost finance assistant.
The question for a Mexican company is how to evaluate that capability with its ERP. The scope here begins after transactions are recorded: comparing a closed period, identifying variances, and building verifiable explanations without delegating financial judgment to a model.
1. What AI financial analysis should deliver
A question such as “Why did maintenance expenses increase?” should produce an answer with five elements:
- Comparison: actual expenses, budget, and prior-period expenses.
- Difference: absolute and percentage variance, with an identified baseline.
- Breakdown: each vendor’s, cost center’s, and expense category’s contribution.
- Evidence: accounting transactions and linked documents.
- Reviewable conclusion: verified facts, interpretations, and open items.
Simply listing the month’s largest invoices is not enough. A vendor may account for a large amount of spending but contribute little to the increase if its amount was similar in the prior period. The analysis must explain the difference, not just the composition of the current balance.
It also helps to separate two questions: “Which transactions account for the variance?” and “What operational situation caused it?” The first can be answered with records; the second may require a service order, a contract, or confirmation from the department manager.
2. Compare actuals, budget, and prior periods
Before querying the AI, finance must define a comparable basis: company, included accounts, currency, period, budget version, and treatment of adjustments. Comparing a closed month with one that is still open can produce a misleading explanation.
Calculations must run through deterministic queries and rules, outside the model’s free-form generation:
| Comparison | Calculation | What it shows |
|---|---|---|
| Actual vs. budget | Actual − budget | Variance from the approved plan |
| Actual vs. prior period | Current actual − prior actual | Change between comparable periods |
| Percentage variance | Difference ÷ baseline × 100 | Relative magnitude of the change |
If the baseline is zero, the percentage should not be presented as a conventional variance: report the absolute change and flag that condition. Negative balances also require a presentation rule agreed upon with finance.
Expense variance analysis should account for reclassifications, accruals, reversals, and foreign exchange differences where applicable. A recorded increase does not necessarily mean higher consumption: it may reflect a classification change or the recognition of a service from another period.
For seasonal activities, the same month of the prior year can provide additional context. It does not replace the budget; it answers a different question.
3. Break down differences without double-counting
Once the total is reconciled, the integration can calculate how much each dimension contributes to the change. The practical sequence is to start with the general ledger account and drill down into cost centers, vendors, and expense categories.
For example, if maintenance expenses increased, the response should identify which cost centers account for most of the variance and which transactions changed within them. It can then distinguish recurring services from one-time work, provided the records support that distinction.
There are three important precautions:
- Reconcile each breakdown to the total. Transactions without an assigned vendor or cost center must appear as “unidentified,” not disappear from the report.
- Avoid duplication. Linking a journal entry to multiple document lines can multiply amounts if the relationship is not properly defined.
- Do not add overlapping dimensions. The increase by vendor and by cost center represents different views of the same expense, not independent differences.
Budget granularity matters, too. If the budget exists only by account and cost center, a vendor-level budget should not be invented. That level can be analyzed against the prior period or shown as a breakdown of actual expenses.
An AI integration with business systems must resolve these relationships before generating explanations. Well-written text does not fix an incorrect data join.
4. Require evidence and separate calculation from interpretation
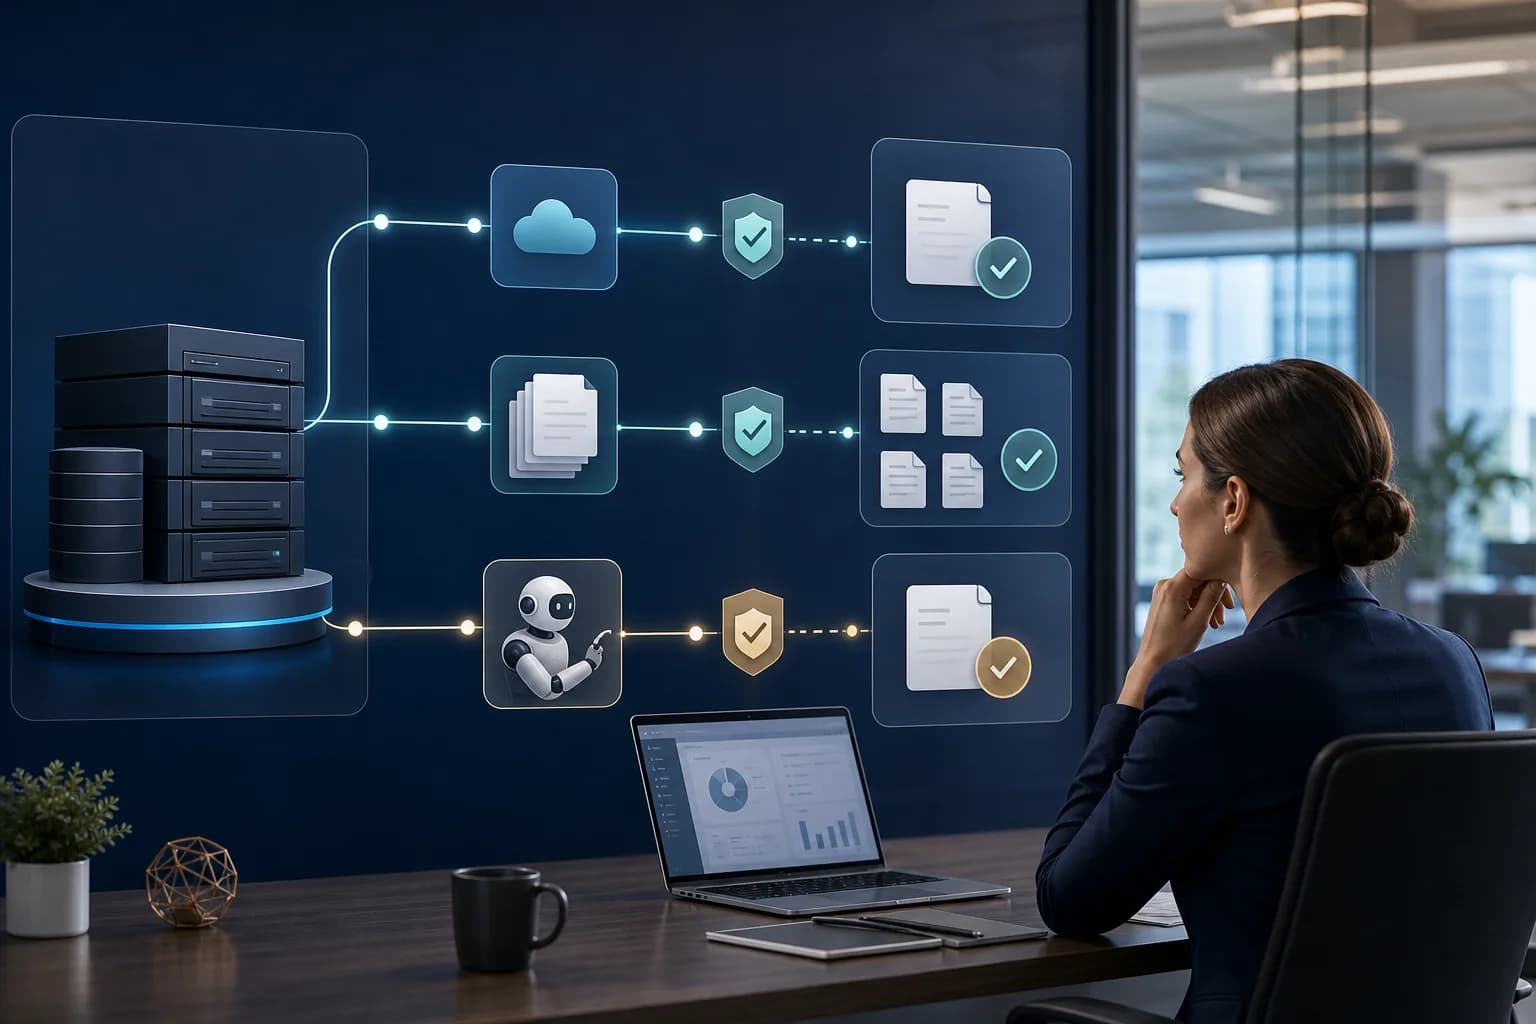
Each material claim should provide a verifiable trail: income statement line item → accounting transactions → supporting records or documents. Depending on the case, the evidence may include CFDI electronic invoices, journal entries, service orders, contracts, or adjustment documents.
A document supports what it contains, not every interpretation. An invoice can substantiate a service and its amount; by itself, it does not prove that an operational failure occurred or that the expense was avoidable.
What the system calculates and what the AI proposes
The data engine retrieves balances, differences, groupings, and contributions. The AI interprets the question, organizes results, consults authorized documentation, and drafts an explanation grounded in those outputs.
A useful response explicitly separates:
- Fact: specific transactions explain part of the variance.
- Support: identifiers, dates, amounts, and links to the corresponding documents.
- Interpretation: a possible operational reason, with its basis.
- Open item: evidence or confirmation needed to accept that interpretation.
If documents are missing, the assistant must say so and identify the amount that lacks linked documentary support. It should not force a complete explanation, either: showing an unexplained remainder is better than inventing a cause.
The finance lead validates both the reconciliation and the business interpretation. Proposed follow-up actions—for example, requesting clarification from the responsible department—can be prepared automatically, but sending or executing them must remain subject to authorization.
5. How to evaluate a pilot using a closed period
The first pilot of AI integrated with an ERP needs a limited scope and acceptance criteria defined before testing.
Define the data and questions
Select a closed period, one business unit, and a few expense accounts with accessible documentation. Include the approved budget, a comparable period, and an analysis prepared by finance as a reference.
Start in read-only mode. Define user-level permissions and retain the queries, sources used, and data version: if the period is later reopened, it must be possible to distinguish the original results from the updated ones.
Test challenging cases
In addition to routine queries, include transactions without linked supporting documents, reclassifications, vendors with different names, and zero budget baselines. The goal is to check whether the system recognizes its limits, not just whether it handles the simplest case well.
Measure and decide
Evaluate these criteria with the finance lead:
- Exact reconciliation of balances and differences with the agreed-upon source.
- Share of the amount explained with accessible evidence.
- Unsupported claims and required corrections.
- Preparation and review time compared with the current process.
- Compliance with permissions and query traceability.
Set thresholds with the company without assuming savings in advance. If the pilot works, a subsequent phase of AI process automation can prepare recurring reports and review tasks while maintaining the necessary approvals.
6. Conclusion: an explanation finance can verify
The value of AI financial analysis lies in connecting a variance to the transactions that make it up and the evidence needed to interpret it. Calculations must be reproducible, hypotheses identifiable, and conclusions reviewed by finance.
At Slashweb, we can work with you to evaluate an ERP integration pilot using a closed period. Contact Slashweb to review the scope and define the accounts, document sources, and acceptance criteria before expanding the solution.
Frequently asked questions
Do I need to switch ERPs to implement this analysis?
Not necessarily. The first step is to evaluate whether the ERP provides access to transactions, master data, and document references through APIs, authorized views, or controlled exports. Feasibility depends on that access and the system’s technical constraints.
Can I use a budget maintained in Excel?
Yes, as long as the approved version, periods, and budget dimensions are identified. The budget must be mapped to the ERP’s accounts and cost centers, and changes to the file must be controlled.
Can the AI access information from multiple companies within the group?
It can be designed to do so if explicit permissions and rules exist for each entity. A consolidated analysis also requires defining currencies, master data, and intercompany eliminations; simply adding the individual reports together is not enough.
Does this type of analysis replace a financial audit?
No. It helps investigate variances and gather evidence for review, but it does not constitute an audit opinion. Its use does not replace the applicable procedures, controls, or professional responsibilities.
Slashweb
Want to apply this in your company?
Book a free call with a specialist and get a tailored proposal.